We appreciate your patience as we respond to a higher than usual volume of inquiries. If you have already left a voicemail or submitted an online complaint, rest assured that your inquiry has been received and we will contact you once it has been reviewed. Please note that duplicate inquiries can further delay our response times. 

Case Study

CASE

Water Damage: Disconnected Drainage Pipe

Synopsis of Complaint:

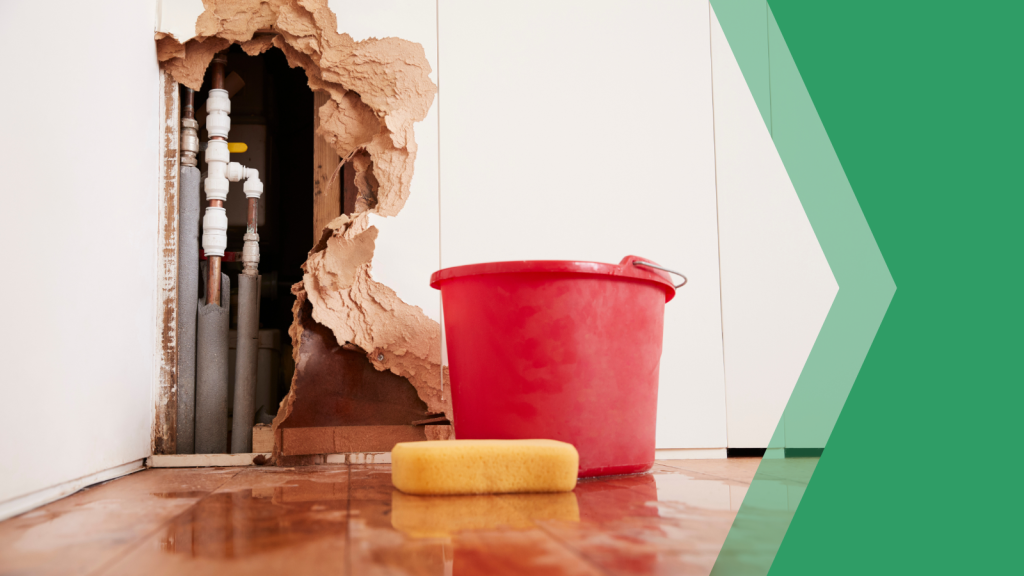
The Consumer experienced property damage due to water loss caused by a disconnected drainage stack pipe behind the drywall.
This pipe extended from the second story bathroom, through the kitchen, and down to the lowest level of the home. The consumer submitted a claim to the insurer, but coverage was denied.

The Insurer rejected the claim, stating that the issue was ongoing rather than sudden and accidental, and therefore not covered.

Additionally, the insurer referenced a specific policy exclusion for rot, mold or damage caused by continuous or repeated seepage or leakage of water.

Review by GIO:

During GIO’s Informal Conciliation, the GIO contacted the Insurer to request a reconsideration of the claim denial for the following reasons:

  • The Consumer promptly reported the claim upon noticing water stains on walls. Acting responsibly, the consumer first consulted a foundation expert to determine the cause of the damage. When this was ruled out, they hired a plumber, who then removed the drywall and discovered the crack and disconnection in the pipe.
  • The policy does not clearly define what constitutes “sudden and accidental”.
  • It is unreasonable to expect consumers to open their walls to inspect for water leaks from pipes concealed within drywall.


GIO’s Investigation Officer discussed the matter with the Insurer acknowledging the policy coverage and the specific exclusions cited. However, they argued that it is unreasonable to expect the homeowner to routinely open drywall to inspect pipes without any signs of a problem.

Regarding the exclusion for mold, the Investigation Officer pointed out that no mold inspection or testing report was provided by the Insurer. Therefore, there was no concrete evidence of mold, only an assumption by the claims adjuster based on photos submitted by the contractor.

Despite this discussion, the Insurer maintained their denial of the claim, leading the case to proceed to mediation.

Resolution:

Through mediation, the insurer and consumer came to a mutually agreeable resolution to the file.

GIO is an independent body set up to help Canadians find a fair resolution to disputes with insurance providers. GIO can provide advice on dealing with your insurance company as a first step. If you are not satisfied with the decision from your provider on your claim, GIO can help resolve your claim. 

If you’d like to submit a claim visit here.

By continuing your navigation on this site, you are accepting the use of cookies. These are designed to improve your user experience on our site by collecting traffic statistics and information on your behaviour.